
Former SEBON ED Giri Stresses Legal Reform and Tech Use for Capital Market Stability
english.ratopati.com · Tue Aug 25 10:21:48 GMT 2026
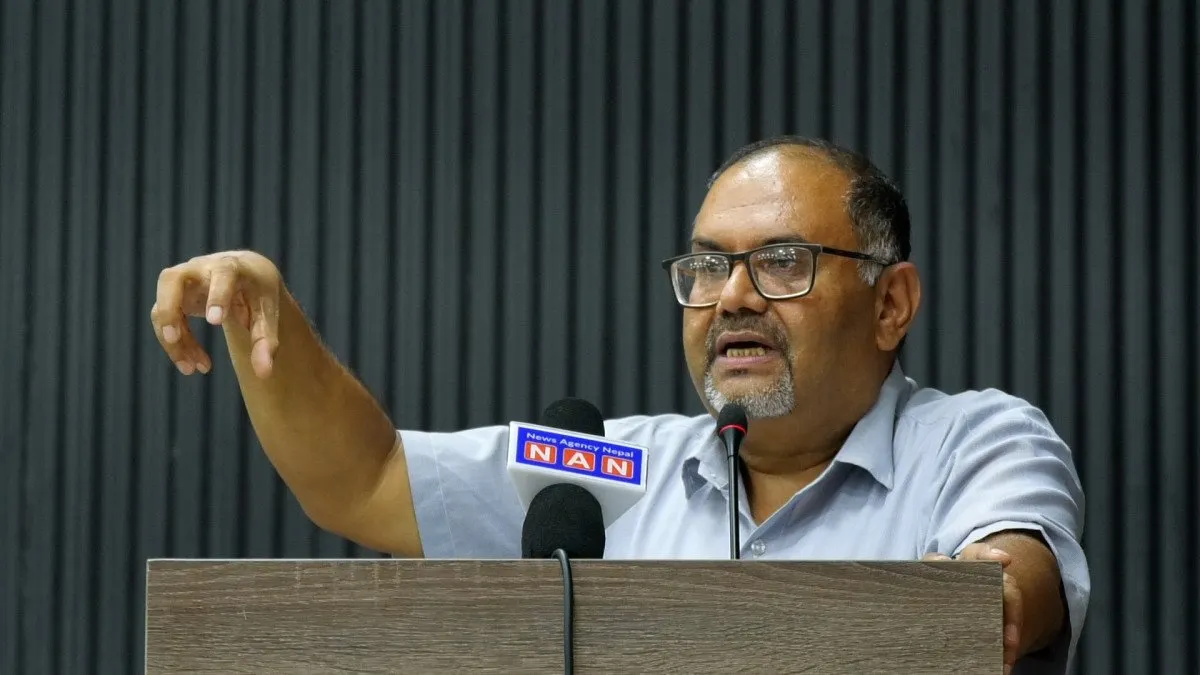
Kathmandu. Former Executive Director of the Securities Board of Nepal (SEBON) Niraj Giri has stated that legal reform and the use of modern technology are indispensable for the stability and development of the capital market. Speaking at a dialogue program on 'Nepal's Capital Market: The Basis of Economic Investment' organized by the Nepali Congress, Giri pointed out the weaknesses in the existing laws and structures. Giri mentioned that the absence of provisions related to financial technology (fintech) in the current law is a major challenge for the market. He argued that the practice of pressuring the government and regulatory bodies to grow the market, instead of developing the fundamental elements for market growth, is wrong. Discussing the lack of real-time monitoring in the market, he warned that the non-use of technology could lead to major economic risks. Presenting the example of a recent broker's liability of 3 billion rupees going unnoticed by regulatory bodies, he emphasized the need for a technology-based monitoring system instead of physical supervision. For reforms, he suggested enacting a new Securities Act and clearly separating the board's operations and market trading activities within that act. Stating that the Nepal Stock Exchange (NEPSE) and CDS and Clearing Limited need restructuring, he mentioned that in a small economy like Nepal, it would be more appropriate to make the existing institutions world-class rather than adding another new stock exchange. Giri said that new financial instruments need to be introduced in the market and it is late to bring Non-Resident Nepalis (NRNs) into the capital market. He stated that high-level coordination between the Ministry of Finance, Nepal Rastra Bank, and the Securities Board is necessary to open the market for NRNs and Foreign Direct Investment (FDI). He expressed confidence that the market would become more dynamic if NEPSE introduced new instruments as a profit-making institution. Mentioning the lack of adequate provisions for fintech in the existing law, Giri said that to grow the market, the government or the Securities Board should not buy shares but rather create a favorable environment, legal basis, and technological development. 'Even though fintech is being used worldwide, its use is not sufficient here,' he said, 'Brokers are still not organized, and there is no effective system for real-time monitoring.' He clarified that due to the non-use of technology, regulatory bodies are unaware even when a large liability is created by a broker, hence technology-based supervision is necessary. According to Giri, the first priority should be the enactment of a new law. 'The operations of the Securities Board and market trading regulations should be clearly separated,' he said, 'The use of technology in supervision should be increased.' Stating that NEPSE and CDS need restructuring, he added that considering the size of Nepal's economy, it would be appropriate to make the current stock exchange capable and technology-friendly according to international standards rather than having another exchange. He said that although there has been long-standing discussion about bringing NRNs into the Nepali capital market, concrete initiatives have not been taken. 'The solution should be sought through coordination between the Government of Nepal, the Ministry of Finance, Nepal Rastra Bank, and the Securities Board,' he said, 'Not only opening the market for FDI and foreign investment, but also creating the legal and institutional arrangements to implement it in practice.' Giri questioned the autonomy of the board and the provisions of the existing Securities Act. He stated that although the Securities Board is called an autonomous institution, in practice, it has to depend on the Ministry of Finance even for સામાન્ય administrative tasks. 'Even though the Ministry of Finance claims the board is autonomous, approval from the ministry is required even to add a single post,' he said, 'There is an interventionist role even when trying to manage human resources according to market needs.' He mentioned that due to the then political instability, the act was forced to remain an ordinance for a long time, and it had many shortcomings when passed by the parliament in 2063 BS. He said that for the balanced development of the capital market, not only brokers but also merchant bankers, dealers, and issue managers have an equal role, but there has not been sufficient legal clarity in this regard in the past. He argued that the lack of a systematic system for the flow of price-sensitive information also causes problems in the market. Discussing the legal history of the capital market, he informed that the draft of a new act was prepared with the support of the Asian Development Bank since 2057 BS to replace the 2040 BS act. He termed it unfortunate that the Securities Act, issued in 2063 BS, has not been amended even after nearly two decades. He concluded that due to the lack of timely legislation, the regulator, investors, and the government have all had to remain in the learning process, and the provision for effective punishment is also weak.
Read full story at source (english.ratopati.com)